Medical professional lending support

Medical Professional Home Loan Services

Compare home loan pathways built around the income, registration and working patterns of Australian doctors, nurses, dentists and allied health professionals. Our medical mortgage brokers help you understand the policies, organise the evidence and progress the application.

Services from our homepage

Home loan support for your healthcare profession

Explore the same four service pathways featured on our homepage. Each pathway is shaped around the way healthcare professionals earn, work and plan their next property move.
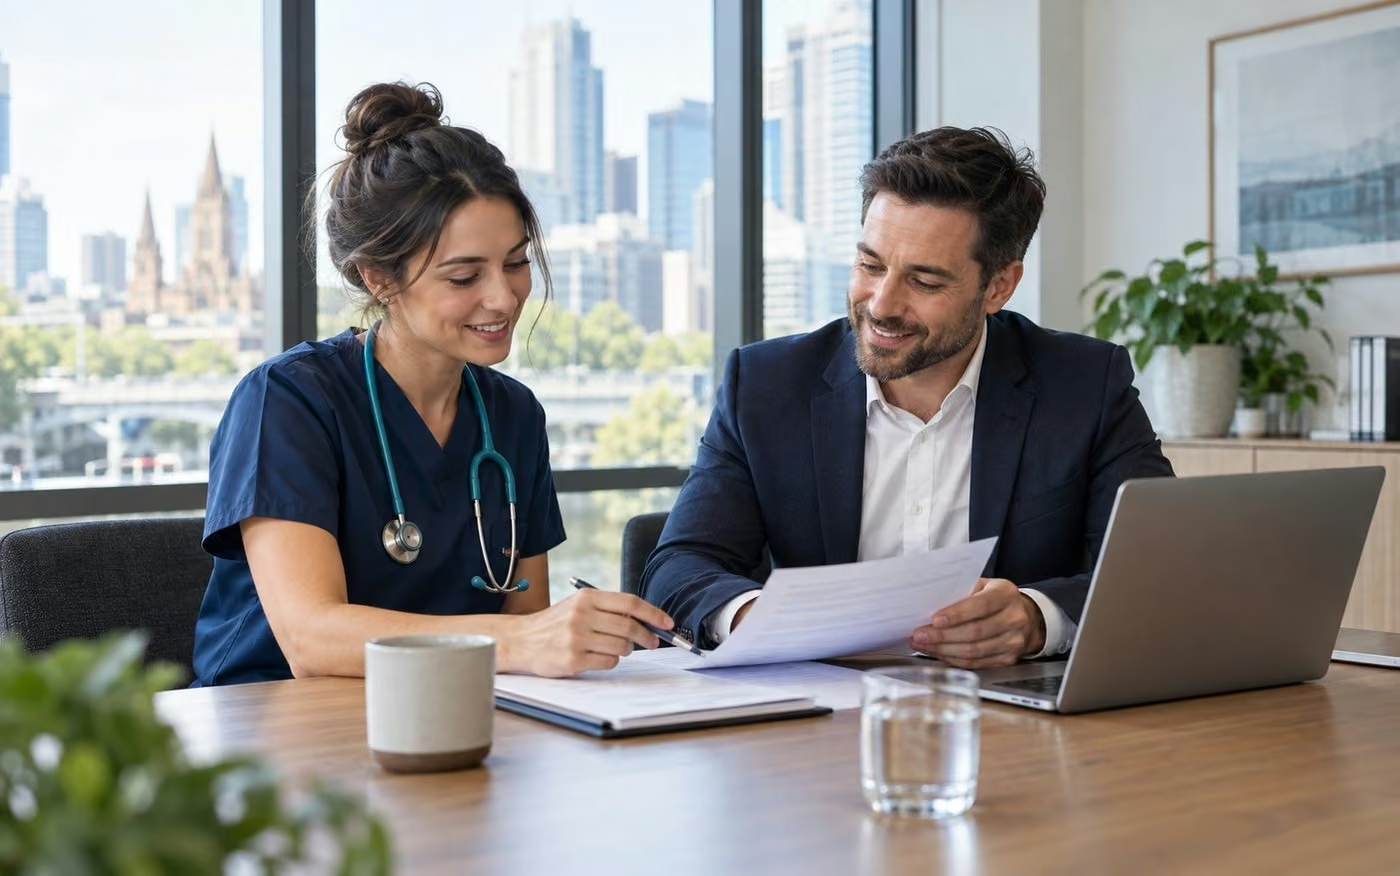
Australian medical professional reviewing home loan options with a mortgage broker

More than an occupation label

Why profession-aware assessment matters

A healthcare payslip does not always tell the whole story. Depending on your role, income may include overtime, on-call payments, penalty rates, allowances, salary packaging, locum work or private-practice earnings.

  • Map each income source to the evidence a lender expects
  • Compare relevant profession and essential-services policies
  • Review LMI, rate, fee, offset and redraw trade-offs
  • Coordinate documents and lender follow-ups
Meet the Medico Home Loans team

A clearer comparison

See the important loan details in one place

Our comparison is built around your actual priorities, not one promotional rate. This illustrative planning board shows the areas we review before a recommendation is made.

What the review can cover

  • Deposit, equity and loan-to-value ratio pathways
  • Possible LMI waiver eligibility and conditions
  • Fixed, variable and split-rate structures
  • Offset accounts and redraw facilities
  • How different lenders may assess additional income
  • Owner-occupied, refinance and investment scenarios
Home loan planning boardReview ready
Income evidenceMapped by source
Lender policiesRelevant options
Loan featuresCompared clearly
Application stepsOrganised

How it works

A clear process from first conversation to settlement

You stay informed while the broker coordinates the research, evidence, application and lender communication.

1

Understand

Discuss your goals, deposit, income, commitments and timing.

2

Compare

Review suitable policies, costs, features and conditions.

3

Prepare

Organise documents and present the income clearly.

4

Progress

Manage the application, updates and settlement coordination.

Clear, responsible guidance

Important information

Eligibility, loan-to-value ratios, lender policy, rates and LMI availability vary by lender and applicant. Approval remains subject to credit assessment, acceptable security and the lender's current criteria.

Useful independent guidance is available from ASIC Moneysmart. Professional registration can be checked through Ahpra.

Reviewed 29 September 2026

General information only. This page does not take account of your objectives, financial situation or needs.

Start with a clear view of your options

Tell us what you are working toward and a medical mortgage broker will explain the next practical step.

Choose a starting point

Which medical home loan service fits your situation?

Start with your profession when you are buying, or with refinancing when you already have a loan to review. The first conversation can cover more than one category, so you do not need to resolve every detail before enquiring.

Prepare a useful first conversation

What will we need to understand about your plans?

Bring your goal, work arrangement, approximate deposit or equity, current commitments and preferred timing. If you are applying with a partner in a different profession, explain both circumstances. The discussion should establish the next questions and evidence needed, not assume an outcome from a job title.

Ask how the broker is paid, which lenders are available for comparison, whether any fee applies to you and why a recommendation fits your needs. Independent guidance on choosing a mortgage broker can help you prepare these questions. You can also explore the home loan guides before arranging a call.

YOUR NEXT STEPPlanning illustration
Your goal
Work arrangement
Deposit or equity
Timing

Helpful answers before you apply

Frequently asked questions about home loans for medical professionals

Understand how profession-based lending policies, LMI waivers, overtime and allowance income may affect an Australian medical professional home loan. These answers explain the essentials, while your eligibility, rate and available features will depend on your individual circumstances and the lender’s current criteria.

Home loans for medical professionals are standard residential loans assessed under lender policies that may better recognise some healthcare professions, income structures or registration status. Depending on the lender and your circumstances, possible benefits can include an LMI waiver, different deposit requirements or broader recognition of regular overtime and allowances. Approval and pricing remain subject to full credit assessment.
No. Eligibility varies by lender, profession, registration status, loan purpose, property, income, loan size and loan-to-value ratio. Doctors and dentists are commonly included in professional policies, while nurse and allied health eligibility can differ more widely. A broker should check the current policy rather than relying on a profession list that may be out of date.
Not automatically. Some lenders may recognise a higher proportion of regular overtime, shift penalties or allowances when the income is stable and supported by payslips or income history. Others apply limits or shading. The suitable approach depends on your employment, consistency of earnings and the lender’s current serviceability policy.
A medical mortgage broker reviews your objectives and financial position, compares suitable options from available lenders, explains costs and features, helps prepare the application and manages communication through to settlement. Mortgage brokers must act in the consumer’s best interests when providing credit assistance.
Start with a short conversation about your profession, income, deposit or equity, property goal and timeframe. Bring recent payslips, identification, details of debts and expenses, and information about your savings or existing loan. The broker can then explain which documents and pathways are relevant to your situation.